How Is PCB Calculated on Bonuses in Malaysia?
- PCB and bonuses: no separate bonus tax in Malaysia: A bonus is treated as additional remuneration for PCB, which can increase the employee’s estimated annual tax and lead to a higher PCB deduction in the month the bonus is paid.
Why does PCB suddenly increase when an employee receives a bonus?
This is a common question for payroll and accounts staff, especially when processing annual bonuses, commissions, arrears or other additional payments.
The first thing to understand is that Malaysia does not have a separate “bonus tax”.
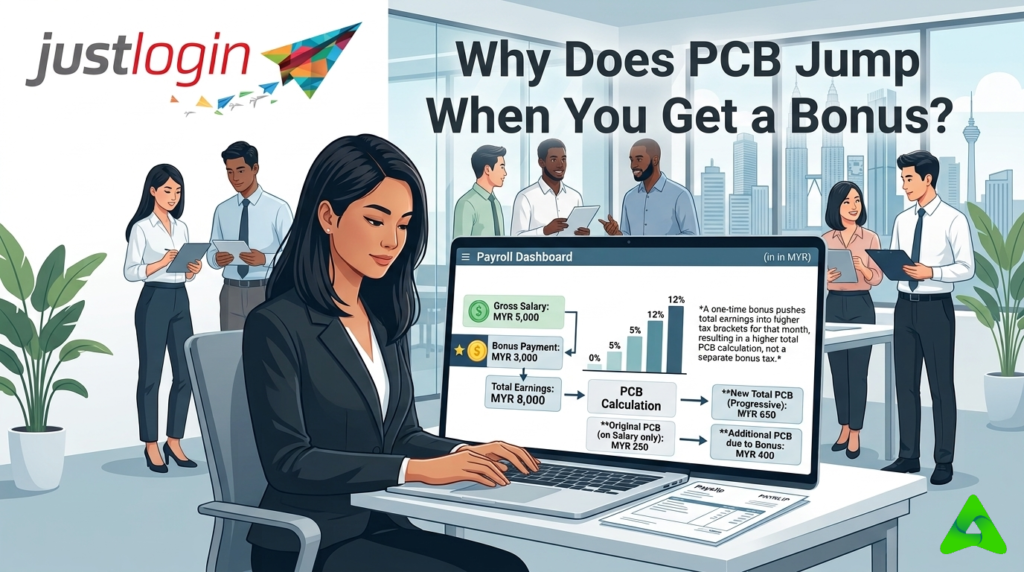
Instead, a bonus is generally treated as additional remuneration for Monthly Tax Deduction (MTD), commonly known as PCB. The additional payment can increase the employee’s estimated tax for the year, which can result in a higher PCB deduction in the month the bonus is paid.
But the calculation is more than simply applying a percentage to the bonus.
Let’s look at it in simple terms.
What is PCB?
PCB, or Monthly Tax Deduction, is the amount an employer deducts from an employee’s remuneration each month and pays to HASiL on the employee’s behalf.
The purpose is to collect the employee’s income tax progressively throughout the year rather than having the employee pay the entire amount at the end of the tax year.
Employers can determine PCB using the prescribed schedule or the computerized calculation method. HASiL’s current 2026 computerized calculation specification sets out separate calculations for normal remuneration and additional remuneration.
What is normal remuneration?
Normal remuneration is generally the employee’s regular monthly pay.
For example:
- Basic salary
- Regular wages
- Overtime
- Certain regular allowances
- Other remuneration that forms part of the employee’s normal monthly pay
The payroll calculation uses the employee’s circumstances and accumulated information during the year to determine the appropriate PCB.
This means PCB is not simply:
Monthly salary × tax rate
There is considerably more to the calculation.
What is additional remuneration?
Additional remuneration is payment that is not part of the employee’s normal monthly remuneration.
For example, HASiL’s 2026 computerized calculation identifies items such as:
- Bonus
- Arrears
- Commission
- Gratuity
- Compensation
- Director’s fees that are not paid monthly
- Income tax paid by the employer on behalf of the employee
- Certain other payments
The important point is that not every payment that is described as a commission or fee should automatically be treated as additional remuneration. The nature and payment frequency matter.
For example, HASiL specifically identifies director’s fees not paid monthly as additional remuneration.
So, what happens when an employee receives a bonus?
Let’s use a simple example.
An employee receives:
Monthly salary: RM8,000
Annual bonus: RM15,000
The employee has already had PCB deducted from their regular salary throughout the year.
When the RM15,000 bonus is paid, payroll does not simply take the bonus and apply one flat tax percentage to it.
Instead, the additional remuneration is incorporated into the prescribed PCB calculation.
The calculation considers the employee’s overall remuneration and other relevant information to determine the annual tax position.
The additional PCB is then determined after taking into account PCB that has already been deducted and other applicable amounts.
A simple way to understand the calculation
You may come across an explanation such as:
Tax after bonus − Tax before bonus = Additional tax
This is useful for understanding the idea behind the calculation, but it should not be treated as the actual HASiL PCB formula.
The actual computerized calculation is more detailed.
In simple terms, the process is closer to:
Calculate the employee’s annual tax position including the additional remuneration
then
Take into account PCB already deducted and other applicable amounts
to arrive at the additional PCB to deduct.
HASiL’s 2026 calculation example shows this approach. For example, one calculation produces annual MTD of RM4,148.40 after including additional remuneration. After deducting accumulated MTD of RM2,859.60, the additional MTD to be deducted is RM1,288.80.
This is why the additional PCB may appear quite different from simply applying a tax percentage to the bonus.
Why does the PCB on a bonus sometimes look so high?
This is where Malaysia’s progressive tax system comes into play.
For resident individuals, different portions of taxable income are taxed at different rates. For example, the current 2026 published individual tax rates include:
- Up to RM5,000: 0%
- RM5,001–RM20,000: 1%
- RM20,001–RM35,000: 3%
- RM35,001–RM50,000: 6%
- RM50,001–RM70,000: 11%
- RM70,001–RM100,000: 19%
- RM100,001–RM400,000: 25%
Higher bands apply to higher taxable income.
This means that when a bonus pushes an employee’s taxable income into a higher tax band, part of the additional income may effectively fall into a higher marginal rate.
However, it is not correct to say that the entire bonus is taxed at the employee’s highest tax rate.
A simple example
Suppose an employee’s taxable income is already around RM90,000 before receiving a RM15,000 bonus.
The bonus could push taxable income beyond RM100,000.
The employee does not suddenly pay 25% tax on the entire RM15,000 bonus.
Instead, different portions of taxable income fall within the relevant progressive tax bands.
This is one reason the PCB deduction on a bonus can look surprisingly large.
What about EPF contributions?
EPF contributions can also affect the calculation.
HASiL’s computerized PCB calculation takes qualifying EPF or approved-fund contributions into account, subject to the applicable limits.
The 2026 calculation specifically identifies EPF contributions relating to additional remuneration separately.
So payroll should not assume that:
Bonus amount = taxable amount used in the final PCB calculation
There can be adjustments before the final PCB amount is determined.
What other information can affect PCB?
The calculation can also depend on information such as:
- Employee’s marital status
- Number and category of qualifying children
- Individual deductions and rebates
- EPF or approved-fund contributions
- Zakat
- PCB already deducted earlier in the year
- Remuneration received from a previous employer during the current year
- Other prescribed deductions or adjustments
This is why payroll needs accurate employee information.
What is TP3?
TP3 is particularly important when an employee joins a new company during the year.
It provides the new employer with information about remuneration, EPF, PCB and other relevant amounts from previous employment during the current year.
This information can then be included in the PCB calculation.
It is therefore not simply a form asking about what the employee earned in previous years.
Why is calculating bonus PCB manually risky?
For a small company with only a few employees, payroll may appear straightforward.
But calculations become more complicated when you have:
- Annual bonuses
- Monthly and non-monthly commissions
- Arrears
- Employees joining during the year
- Different employee tax situations
- EPF contributions
- Tax reliefs and deductions
- Changes in salary during the year
- PCB already deducted in previous months
A spreadsheet can certainly help with record keeping, but the person preparing payroll still needs to understand which figures should go into the calculation and how the prescribed method works.
A small mistake can result in the wrong amount of PCB being deducted.
Payroll software can make the process easier
This is where a good payroll system can be useful.
The objective is not simply to produce a payslip.
A good payroll system should help with the underlying calculations and keep track of employee information and cumulative figures needed for payroll processing.
HASiL itself provides for PCB to be determined using a computerized calculation method, and employers are responsible for making the required monthly deductions and remitting them within the prescribed timeline.
For businesses processing bonuses and other additional remuneration, having the right payroll process can reduce manual calculations and the risk of errors.
Don’t assume a high PCB deduction means something is wrong
When an employee sees a large PCB deduction from their bonus, the first reaction may be:
“Why is so much tax being deducted?”
It does not necessarily mean the employer has calculated it incorrectly.
The deduction may be the result of the prescribed annualized calculation, taking the additional remuneration into account together with the employee’s accumulated remuneration, PCB already deducted, applicable deductions and other relevant information.
The important thing is to understand how the amount was arrived at.
PCB is a monthly tax deduction mechanism. It is not necessarily the employee’s final tax liability for the year.
The employee’s final tax position is ultimately determined when the annual income tax return is submitted.
A practical checklist for payroll staff
Before processing a bonus, make sure you have:
- The correct bonus amount
Confirm the approved bonus before running payroll. - The correct employee information
Check marital status, children, EPF information and other relevant details. - Current-year previous employment information
For employees who joined during the year, check whether TP3 information is required. - Previous PCB deductions
Make sure cumulative PCB figures are up to date. - Correct treatment of the payment
Determine whether the payment should be treated as normal remuneration or additional remuneration under the applicable rules. - Correct EPF treatment
Check whether EPF applies and how the contribution affects the calculation. - The resulting PCB
Review the additional PCB before finalising payroll.
The bottom line
Calculating PCB on a bonus is not simply a matter of taking the bonus amount and multiplying it by a tax rate.
The calculation considers the employee’s wider tax position, including accumulated remuneration, additional remuneration, PCB already deducted and applicable deductions and contributions.
The good news is that payroll staff do not have to perform all of these calculations manually.
At Adventus Business Consult, we help Malaysian SMEs explore practical cloud payroll solutions and outsourced payroll support, including solutions that can help simplify payroll processing and statutory calculations.
If your payroll is becoming more complicated as your business grows, it may be time to look at a better way of managing it.
Need help reviewing your payroll process? Talk to Adventus Business Consult for a no-obligation discussion.